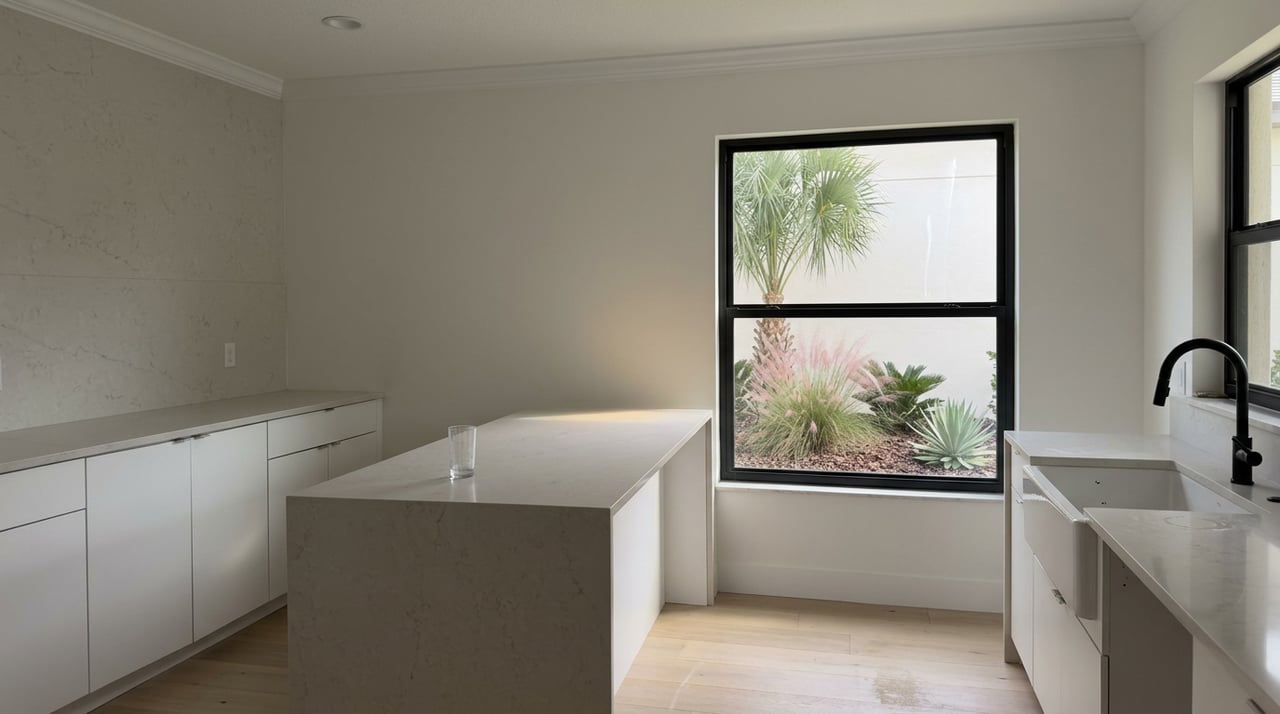
Selling in Two Rivers? Your Real Competition Isn't Another Resale Home
August 20, 2026
August 20, 2026
A homeowner in Two Rivers lists a house built in 2024. It shows like new because it practically is. The listing copy leans on that: barely lived in, meticulously maintained, upgrades beyond builder standard. It is a smart pitch. It is also, in this particular master plan, not quite enough. Half a mile away, a national builder is running a rate buydown on a brand-new home with a similar floor plan, and the buyer walking through both houses this weekend is doing math the seller never sees.
That is the part of selling in Two Rivers that a standard comparative market analysis misses. For resale sellers, nearby new construction is another factor to weigh.
Two Rivers is still being built. Roughly a dozen national builders, including D.R. Horton, Pulte, Lennar, M/I Homes, William Ryan Homes, Park Square Homes, Homes by WestBay, and Taylor Morrison, are actively selling new construction inside the same 6,000-acre master plan straddling the Wesley Chapel and Zephyrhills line. Industry sources have recognized the community as one of the region's top-performing master plans, and that recognition is doing exactly what it is designed to do: it keeps buyers touring model homes before they ever open the MLS.
For a resale seller, this changes what a comparable sale actually looks like. Your buyer isn't only cross-shopping your street against the next subdivision over. They're standing in a design center picking quartz colors for a home that doesn't exist yet, weighing that experience against yours. A community still selling new inventory offers buyers another set of options alongside resale homes.
The sticker prices can look close enough to ignore. They aren't, once financing enters the picture. Builders in Two Rivers have spent 2026 leaning on financing incentives rather than price cuts, and those incentives change a buyer's monthly payment in ways a resale seller can't easily match without a lender relationship of their own.
| Builder | Incentive type | Detail found in research |
|---|---|---|
| M/I Homes (Shortgrass) | Rate buydown | Rates from 2.88% year one, 3.88% year two, 4.88% years three through thirty, tied to quick move-in homes closing by August 31, 2026 |
| Pulte Homes | Builder Forward Commitment | Rate lock on a pool of funds through Pulte Mortgage, available on qualifying new home agreements only |
| Homes by WestBay | Temporary rate offer | A 4.99% 30-year fixed rate on select quick move-in homes, an offer that ran through July 21, 2026 |
| D.R. Horton | Agent commission structure | Up to 4% commission to a buyer's agent on contracts written between January 1 and December 31, 2026 |
Two things stand out here. First, these offers have different timelines, which means the builder next door might be running a completely different deal than the one that convinced your buyer's friend to sign three months ago. Second, D.R. Horton's buyer-agent commission offer is one difference resale sellers may want to consider when comparing their homes with new construction.
Financing incentives do not show up on a list-price comparison; they affect the buyer's monthly payment, which can shape an offer. The commission offer is a separate consideration for resale sellers comparing new construction.
The clearest example of how far this competition extends is Lennar's Two Rivers community, which has partnered with Opendoor to buy a prospective buyer's current home directly. Lennar's own marketing describes the appeal plainly: skip the hassle of listing, months of showing and juggling double mortgages.
That single sentence explains why a resale seller's toughest competitor in Two Rivers isn't always another homeowner. Sometimes it's a builder who has removed the exact friction that makes a move-up buyer hesitate. A family that would otherwise need to list their current home, sit through showings, and coordinate a double closing can instead sell straight to Opendoor through the builder's process and walk into a brand-new Lennar home on one timeline. The resale seller isn't just losing a buyer to a nicer floor plan. They're losing a buyer who never had to become a seller of their own in the traditional sense at all.
Two Rivers resale activity over the trailing year as of May 2026 shows 519 homes changing hands through the Zephyrhills MLS, an average list-to-sale ratio of 99%, and a price range running from $309,900 to $1,329,000. On the surface, a 99% list-to-sale ratio sounds like a seller's market. Sellers are getting close to what they ask.
The number worth sitting with is the average time it took to get there: 93 days. Compare that to Pasco County as a whole, where homes sold in an average of 48 days over the three months ending April 2026. A resale home in Two Rivers is taking almost twice as long to sell as the countywide average, even while landing within striking distance of its asking price.
That combination can make pricing and timing important. New-construction incentives and trade-in options are additional factors sellers may consider when planning a sale.
None of this means resale homes in Two Rivers are hard to sell. It means the pricing and marketing conversation has to start somewhere different than a typical resale comp pull.
A few things matter more here than in an established, built-out neighborhood:
For sellers, the longer time on market makes it especially important to account for builder incentives, which can change while a home is listed.
Does it matter which builder is closest to my home? Somewhat. A William Ryan or M/I Homes section running an active rate buydown creates more immediate competition than a village that's already sold out and moved into resident hands.
Should I wait until The Landing or a nearby amenity center opens before listing? That depends on your timeline more than the market. Amenity openings can shift buyer interest, but builder incentives change on a much shorter cycle and are the more immediate factor in most offers right now.
How do I know what a builder's incentive is actually worth in dollars? A rate buydown's value depends on the loan amount, the buydown structure, and how long the buyer plans to stay in the home. It's worth running the math on a specific competing listing rather than assuming a headline rate translates evenly across price points.
If you're weighing whether to list a resale home in Two Rivers, or trying to figure out what a specific builder incentive down the street actually means for your pricing strategy, Platinum Property Collective can walk through the current builder landscape with you before you set a number. Schedule a free consultation and let's price your home against what buyers are really comparing it to.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.
Stay up to date on the latest real estate trends.
We are committed to guiding you every step of the way—whether you're buying a home, selling a property, or securing a mortgage. Whatever your needs, we've got you covered.
Platinum Property Collective Group
Home Run Team of Tampa Bay Powered by The Wilkins Way Llc
Tampa, FL